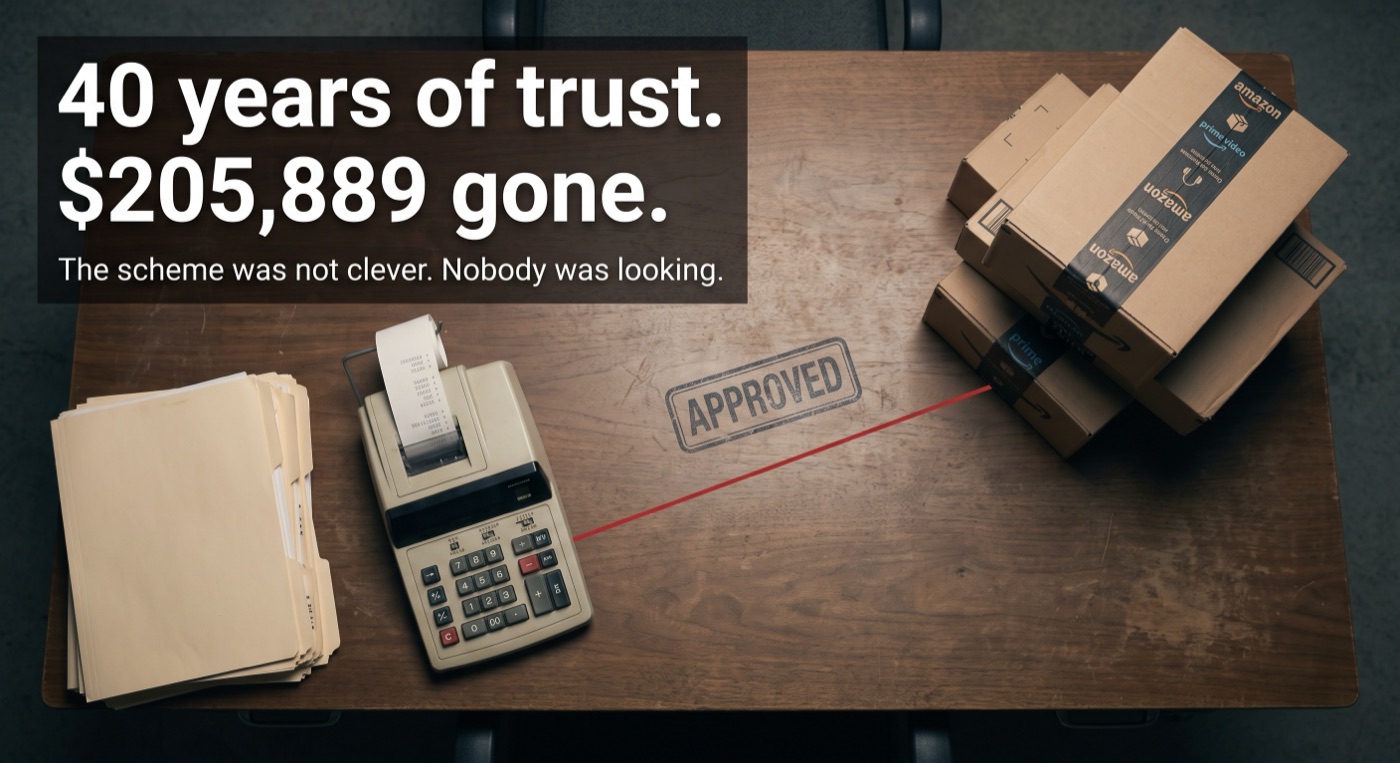
On September 14, 2026, Angela Sue Conley, 60, of Bristol, Virginia, pleaded guilty in federal court in Abingdon to one count of wire fraud and one count of mail fraud. She had worked as the bookkeeper for a Bristol business, identified in court records only as "Company A," for more than 40 years until she was terminated in February 2025.
Between January 2020 and February 2025, Conley caused $205,889 in fraudulent transactions. She ran payroll, had access to the company's bank accounts, and carried a company credit card. She sent 38 unauthorized wire transfers totaling $139,246 to her personal Capital One credit card account, moved money to her personal checking account, made 474 personal Amazon purchases on company funds, and paid her own bills to Verizon, BVU Authority, and the Virginia Department of Taxation from the business account. The December 2025 indictment also alleged transfers to her own bank and 401(k) accounts and an altered paycheck; those allegations were not part of the plea. The FBI Richmond Division and the Washington County Sheriff's Office investigated.
Under the ACFE Fraud Tree: asset misappropriation through fraudulent disbursements, running three schemes at once. Electronic payment tampering, personal purchases with company funds, and an alleged payroll scheme, all concealed by nothing more than tenure and unreviewed payment authority.
On September 14, 2026, a 60 year old woman named Angela Sue Conley walked into federal court in Abingdon, Virginia and pleaded guilty to wire fraud and mail fraud. She had worked as the bookkeeper for a Bristol, Virginia business for more than forty years. Over the last five of those years, she took $205,889.
The Department of Justice press release is short. It is worth reading anyway, because the mechanics are so ordinary that most owners will recognize their own company in it.
Conley's job included payroll. That job came with two things: access to the company's bank accounts and a company credit card. Those two pieces of access were all the scheme required.
She sent 38 wire transfers from the company's bank account to her personal Capital One credit card account. Those alone totaled $139,246, roughly two thirds of the entire loss. She also moved funds to her personal checking account.
She used company money for 474 personal purchases from Amazon. High heel shoes. Earrings. Pool covers. Each item shipped by mail or commercial carrier, which is why the federal charges include mail fraud alongside wire fraud.
She paid her own bills directly out of the company's account. Verizon. BVU Authority, the local utility. The Virginia Department of Taxation, for her personal tax obligation.
The indictment returned in December 2025 went further, alleging transfers into her own bank and 401(k) accounts and an altered paycheck. Those allegations were not part of what she admitted, so they remain allegations.
Under the ACFE fraud tree, this is asset misappropriation through fraudulent disbursements. It is not one scheme. It is three, running side by side.
The wires to her credit card and checking account are payment tampering in its modern electronic form. The employee authorized to initiate payments simply initiates payments to herself.
The Amazon purchases and the payments to Verizon, the utility, and the Department of Taxation are personal purchases made with company funds. On the general ledger, a payment to a phone carrier does not look like theft. It looks like overhead.
The altered paycheck allegation, if proven, is a payroll scheme: falsified wages.
Three separate typologies inside one job function. That is what concentration of duties buys you.
She did not build shell vendors with names designed to mimic real suppliers. She did not forge bank statements. There is no reported evidence of an elaborate ledger rewrite. Compared to the cases that make headlines, where a controller spends years engineering a false vendor ecosystem, this one looks almost lazy.
It still ran for five years.
The concealment was not technical. It was tenure. Forty years of service is its own control override. Nobody audits the person who has handled the books since before half the staff was hired. Nobody wants to be the one who asks her for documentation. And the one person who would normally catch a payment anomaly was the person making the payments.
The ACFE's Occupational Fraud 2026: A Report to the Nations, drawn from 2,402 cases, puts numbers on that instinct. Perpetrators with more than ten years of tenure caused the highest median losses of any group, at $200,000. Long tenure accumulates access, institutional knowledge, and the benefit of the doubt.
The same report found the median scheme runs 12 months before detection, and schemes caught inside six months carry a median loss of $40,000. This one ran 62 months.
The 2026 report puts the median loss per case at $104,000, and found that the smallest organizations suffer the highest median losses of any size group.
Those losses land on thinner margins. A six-figure loss at a company doing $8 million in revenue is a bad year. At a company doing $3 million with an 8 percent margin, it can be most of the year's profit, gone.
The control gap is structural. Most large organizations have a formal channel for reporting concerns; only about a quarter of small businesses do. Tips are still the most common way fraud gets caught, but a tip needs somewhere to go.
That is the Bristol company's profile. Small enough that one person owned the payment function, small enough that there was no internal audit, and small enough that nobody was going to volunteer a concern about a forty year employee.
None of these tests are exotic. All of them require looking at the full population of transactions rather than a sample, and all of them require someone outside the payment function to run them.
Match employee data against payment destinations. Compare bank routing and account numbers, addresses, and phone numbers across the employee master and the AP and banking data. A company wire landing at an employee's personal credit card account is not a judgment call. It is a hit.
Profile the payees that are not vendors. List every recipient of company funds over the period, then subtract the vendor master. What remains should be payroll, taxes, and lenders. Verizon, a residential utility account, and a personal state tax payment do not belong on that list.
Test disbursement authority against disbursement activity. Identify everyone who can initiate a payment, then look for payments where the initiator is also the beneficiary, directly or one step removed.
Recompute payroll from the source. Tie gross pay per employee back to the authorized rate and hours, every period. Altered paychecks show up as variances, not as missing records.
Run card spend against a business-purpose test. Categorize every card transaction by merchant. Consumer retail, apparel, and home goods concentrated on one cardholder is a pattern, not a coincidence, especially at 474 transactions.
Look at velocity, not just amount. No single wire is going to trip anything. Thirty eight of them to the same destination over five years is a shape. Full-population analysis sees shapes. Sampling sees individual transactions and concludes they look fine.
If a single person handles the books in your business, here are five things that cost almost nothing.
Have bank statements delivered somewhere the bookkeeper cannot intercept, and open them yourself. Not the reconciliation report. The statement.
Pull a list of every payee from the last twelve months and read it. You will recognize almost every name. Circle the ones you do not.
Require dual authorization for any outbound wire or ACH over a threshold you set, and make yourself the second signature.
Review the vendor master for additions in the last twelve months, and require documentation for each one.
Once a quarter, confirm the number of employees on the payroll register matches the number of people who work for you, and that your own approval sits behind every rate change.
None of that replaces a real review. All of it raises the cost of running a scheme undetected.
Most owners assume the choices are doing nothing or paying a forensic accountant by the hour for a months-long investigation. That gap is a big part of why schemes like this run for five years. A fixed-fee, full-population review of the exports you already have, payroll, payables, bank and card statements, sits in between. It is the kind of work a Business Health Check is built to do, and it is worth considering if you are a few years from selling, if cash feels tighter than revenue says it should, or if one person touches both the books and the bank.
The Bristol company will spend years trying to recover $205,889 through restitution. A review would have cost a fraction of that and found it in the first year.
I've spent 15+ years investigating financial crime in law enforcement, fintech, and the credit bureaus. I write these briefs so the patterns are harder to miss. If this one hits close to home, I'm easy to reach.